Eligible Property Types
- Duplexes, triplexes, and fourplexes
- 2 to 8 unit multifamily buildings
- Small apartment properties
- Mixed-use buildings
- Turnkey or value-add multifamily
- STR, long-term or multifamily assets
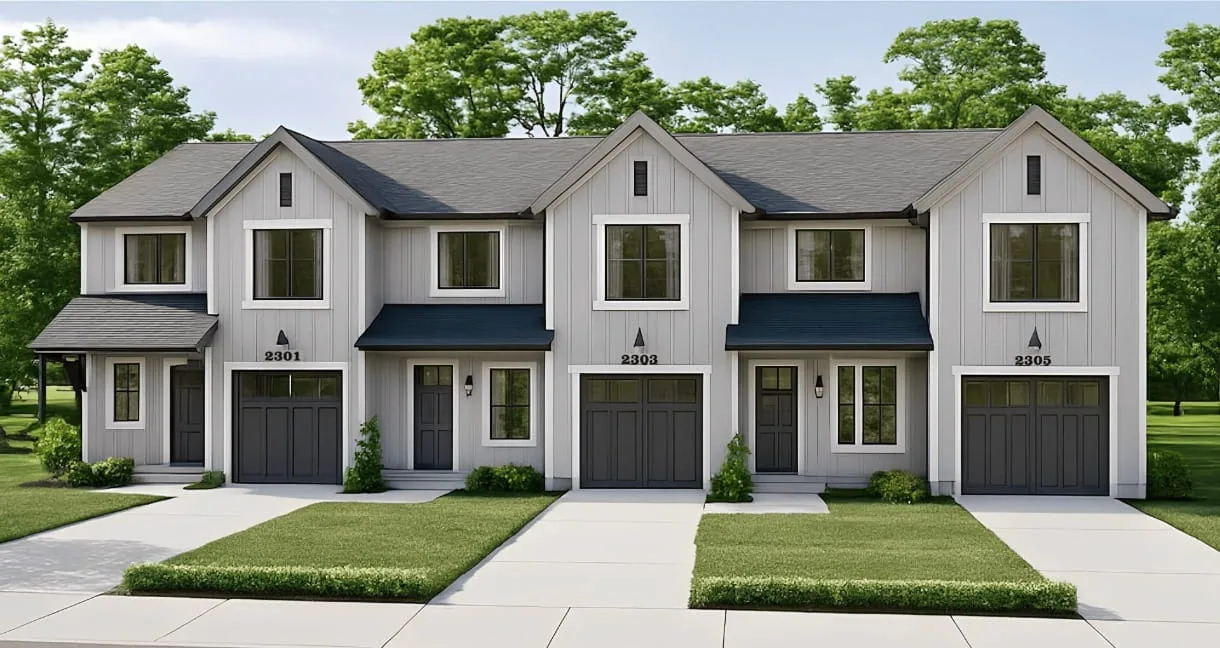
Multifamily DSCR loans allow investors to qualify using the property's cash flow, not personal income. Whether you're acquiring a new asset or refinancing an existing building, DSCR financing provides streamlined underwriting and competitive terms.
Whether you're acquiring a new short term rental property or refinancing an existing investment property, DSCR financing is the perfect loan program for multifamily real estate.
To qualify for multifamily loans, lenders review primarily the property's projected rental income, not your personal tax returns, W-2's, or DTI.
Soft-pull pre-approval and rent-based analysis.
We match your deal with the best DSCR lender for multifamily loans.
Appraisal includes market rent survey, income multipliers, and DSCR calculation.
Close the loan in your LLC or business entity with minimal documentation.
Crestmark Lending specializes in multifamily DSCR loans nationwide, delivering fast approvals, low rates and investor-focused financing from specialists who understand DSCR financing.
Why Choose Crestmark LendingAt Crestmark Lending, multifamily DSCR loans are designed for real estate investors purchasing or refinancing 2 to 8 unit properties like duplexes, triplexes, and fourplexes. Instead of using personal income, we qualify you based on the property's rental income, making it easier to scale your portfolio without traditional income documentation.
For larger properties, Crestmark Lending also offers commercial DSCR loan options for 2 to 8 unit multifamily buildings. These programs are still driven by property cash flow, with flexible guidelines tailored to experienced investors and growing portfolios.
No. Multifamily DSCR loans do not require traditional personal income documentation such as W-2s, pay stubs, or tax returns. Instead, qualification is based primarily on the property's rental income and its ability to cover the proposed mortgage payment (the debt service coverage ratio).
While a personal guarantee is typically required, underwriting focuses on the asset's cash flow, credit profile, and overall investment strength, not the borrower's personal income.
Yes. Multifamily DSCR loans can be used for both purchases and refinances.
Investors commonly use DSCR financing to acquire new multifamily rental properties or to refinance existing assets to lower their rate, pull cash out, or restructure the loan for better long-term cash flow. Because qualification is based on the property's rental income, the process remains streamlined for both scenarios.